AVRA Default Statistics
AVRA Default Statistics is an interactive user interface product which provides end-to-end management of the entire suite of statistical models.
AVRA Default Statistics is a GUI based product that aides institutions manage IFRS 9, Basel & IRRBB models for which Financial Institutions have either adopted benchmark models, hired external consultants or recruited skilled team of resources.
With the advent of new regulations, Models have come under rigorous scrutiny by Auditors/Regulators, and Financial Institutions are expected to defend these ‘black-box’ models even when they don’t fully understand them. AVRA Default Statistics provide an efficient alternative that is cost-effective, robust & user-friendly and offers model transparency along with process efficiency.
Mrs. Soumya V. S.
General Manager India Branch & Head of AI & Solution Development
Mrs. Soumya V. S. is a technology leader, entrepreneur, and software architect with over 20 years of experience in enterprise software development, artificial intelligence, digital transformation, and product engineering. Throughout her career, she has successfully led the design, development, and delivery of innovative technology solutions across India, the UAE, and the Middle East, specializing in AI, ERP, web and mobile applications, and enterprise digital platforms.
She currently serves as the General Manager – India Operations at TeleWyx Digital Solutions, where she leads the company’s Research & AI Development Center in India. In this role, she oversees product innovation, AI research, software engineering, and the development of next-generation digital banking, fintech, enterprise, and intelligent automation solutions, driving TeleWyx’s technology strategy and product roadmap.
Prior to joining Telewyx, Mrs. Soumya founded and successfully led several technology ventures, including Design-Pods, Oracuz Info Tech International LLC (UAE), and Oracuz Info Tech (India). Under her leadership, these organizations delivered enterprise software, AI-powered platforms, ERP systems, Oil & Gas inspection solutions, automation platforms, and custom web and mobile applications for clients across multiple industries.
Earlier in her career, she held senior software engineering positions with Tahcom (Saudi Arabia), Trinity Technologies, Tandem Infotech, and Simage Technology, where she gained extensive experience in software architecture, enterprise application development, and mentoring technical teams while delivering mission-critical business solutions.
Mrs. Soumya possesses extensive expertise in Artificial Intelligence, Machine Learning, Natural Language Processing (NLP), Computer Vision, MERN Stack, Flutter, Python, .NET technologies, cloud platforms (AWS, Azure, GCP), ERP systems, and enterprise solution architecture. She has successfully delivered numerous digital transformation initiatives across sectors including banking, healthcare, hospitality, oil & gas, education, retail, logistics, and government services.
An accomplished product innovator, Ms. Soumya has also developed several proprietary software products and AI-powered platforms, reflecting her passion for innovation and emerging technologies. Her leadership combines deep technical expertise with strategic business vision, enabling organizations to leverage technology for sustainable growth, operational excellence, and digital transformation.
Mr. Basel Mahmoud Ashraf
General Manager
Mr. Basel Mahmoud Ashraf is a seasoned Kuwaiti businessman with more than three decades of experience across banking, oil and gas administration, real estate development, contracting, and private-sector enterprise leadership. Over the years, he has built a diversified business portfolio focused on asset development, infrastructure delivery, strategic investments, and sustainable commercial growth within Kuwait’s evolving economic landscape.
Throughout his career, Mr. Ashraf has held leadership positions across multiple business ventures, with a strong specialization in real estate investment, construction project execution, operational management, and business structuring. He is widely recognized for his ability to identify emerging opportunities and transform them into scalable and sustainable business operations, combining financial discipline with practical execution in complex and high-value project environments.
He is the Founder and General Manager of TeleWix Solutions Company, a diversified technology and services-oriented enterprise focused on digital innovation, emerging technologies, and strategic private-sector opportunities.
In addition, he is the Founder and Managing Partner of Jaliah International Real Estate Company, where he leads strategic land acquisition, investment planning, and real estate development initiatives. He is also the Founder and Managing Partner of Bsslyi General Contracting Company, overseeing construction and infrastructure projects with a focus on operational excellence, regulatory compliance, quality delivery, and long-term sustainability.
Earlier in his professional career, Mr. Ashraf gained valuable foundational experience within Kuwait’s financial and energy sectors through positions at National Bank of Kuwait, where he worked in credit operations and risk assessment, and Kuwait Oil Tanker Company, where he developed extensive operational and administrative expertise within a state-owned enterprise environment.
He remains actively engaged within Kuwait’s business community and maintains affiliation with the Kuwait Chamber of Commerce and Industry (KCCI). Fluent in both Arabic and English, he brings together financial acumen, operational leadership, commercial strategy, and international business expertise.
Today, his professional focus continues to center on expanding investment opportunities, strengthening real estate and contracting operations, fostering strategic partnerships, and creating long-term value through disciplined execution and sustainable business growth.
Basel Mahmoud Ashraf represents a business leadership profile defined by execution capability, sectoral diversity, entrepreneurial vision, and long-term value creation within Kuwait’s private-sector economy.
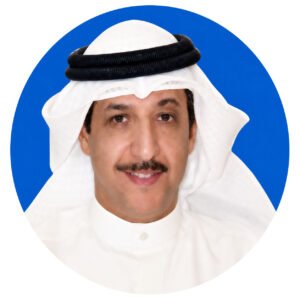
Sheikh Mishal Shamlan Abdulaziz Al Sabah
Chairman
Sheikh Mishal Shamlan Abdulaziz Al Sabah is a distinguished Kuwaiti leader with decades of senior executive experience in government administration, defense operations, financial governance, and institutional modernization within the Ministry of Defense of Kuwait. Renowned for his strategic leadership and operational excellence, he has played a pivotal role in advancing procurement governance, budgeting frameworks, financial oversight, and public-sector digital transformation initiatives.
Throughout his distinguished career, he held several prominent leadership and executive positions within the Ministry of Defense, including Assistant Undersecretary roles overseeing Local Procurement, Planning and Information Systems, and Financial and Administrative Affairs (Acting). He also led and managed critical departments such as Local Procurement, Accounts, Payroll, and Budgeting, while overseeing core functions related to financial auditing, procurement compliance, disbursement control, governance frameworks, and administrative operations. His leadership reflects extensive expertise in defense administration, institutional governance, financial systems, and technology-driven modernization.
In addition to his executive responsibilities, Sheikh Mishal served on numerous high-level committees and strategic governance bodies within the Ministry of Defense, contributing significantly to policy development, procurement regulation, and national budget oversight. His committee roles included:
Building on his extensive public-sector leadership experience, he is also the Founder and Chairman of TeleWix Solutions Company, a Kuwait-based digital technology and software solutions company focused on delivering innovative platforms, digital transformation services, and advanced technology-driven solutions across public and private sector markets.
His national service includes active participation in the liberation of Kuwait in 1991, for which he was awarded the Liberation Medal alongside several distinguished national and institutional honors recognizing his service and contributions.
Sheikh Mishal is widely respected for his enduring contributions to public-sector excellence, governance modernization, procurement reform, financial stewardship, and the advancement of institutional and digital transformation initiatives in Kuwait.
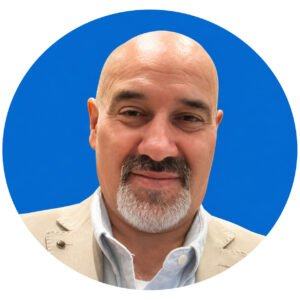
Mr. Zaher El Khatib
Chief Executive Officer
Mr. Zaher El Khatib is a seasoned technology and business leader with more than 29 years of experience in the banking and financial services industry. He serves as Partner and Chief Executive Officer of TeleWyx Digital Solutions in Kuwait, where he leads the company’s strategic vision, innovation agenda, digital transformation initiatives, and regional expansion.
Throughout his career, Mr. El Khatib has built a strong track record in leading large-scale digital transformation programs across the banking sector, with deep expertise in Islamic digital banking, AI-driven financial solutions, business transformation, fintech integration, core banking platforms, regulatory compliance frameworks, and strategic partnerships. His leadership blends business strategy with advanced technology execution, enabling financial institutions to modernize operations, enhance customer experience, and achieve scalable growth.
His core areas of specialization include Islamic and digital banking solutions, Anti-Money Laundering (AML), IFRS 9 implementation, enterprise risk management, and regulatory technology, supporting financial institutions in strengthening operational resilience, ensuring compliance, and accelerating innovation. He is recognized for driving revenue growth, market expansion, and competitive differentiation through innovative Shariah-compliant banking solutions powered by robust digital platforms.
Mr. El Khatib spent 27 years at Path Solutions and Azentio Software, where he held senior leadership positions and played a pivotal role in the development, implementation, and global expansion of world-class Islamic and digital banking platforms, including “iMAL,” a Shariah-compliant core banking solution certified under AAOIFI standards. During this period, he led complex transformation programs and enterprise-scale implementations for financial institutions across multiple international markets, delivering mission-critical banking and financial technology solutions.
Prior to co-founding TeleWyx Digital Solutions, he served as Board Advisor to Kurdistan International Islamic Bank, advising on Islamic digital transformation, fintech adoption, and banking modernization strategies. He also held the position of Chief Business Officer at WorldLink Inc., a U.S.-based technology startup, where he led business development and strategic growth initiatives.
Mr. El Khatib is widely recognized for his advisory expertise in Shariah-compliant financial products, core and digital banking transformation, fintech integration, and AI-driven banking innovation, with consulting experience across multiple international financial institutions.
At TeleWyx Digital Solutions, he continues to focus on driving innovation, building strategic partnerships, and delivering next-generation technology solutions that align financial services with digital transformation objectives, ensuring sustainable growth and long-term value creation.